Process mining can reveal where business processes are inefficient, where exceptions occur, and how work moves across enterprise systems. But identifying an opportunity for improvement is not the same as delivering a financial return.
For organisations that have already invested in process mining, this distinction becomes increasingly important. Dashboards may provide greater visibility, and analysis may uncover previously hidden inefficiencies, but finance leaders still need to understand what has changed as a result.
Has the organisation reduced operating costs? Have cycle times improved? Has working capital been released? And can those improvements be credibly attributed to actions informed by process mining?
Measuring process mining return on investment (ROI) requires organisations to connect operational insights with measurable business outcomes.
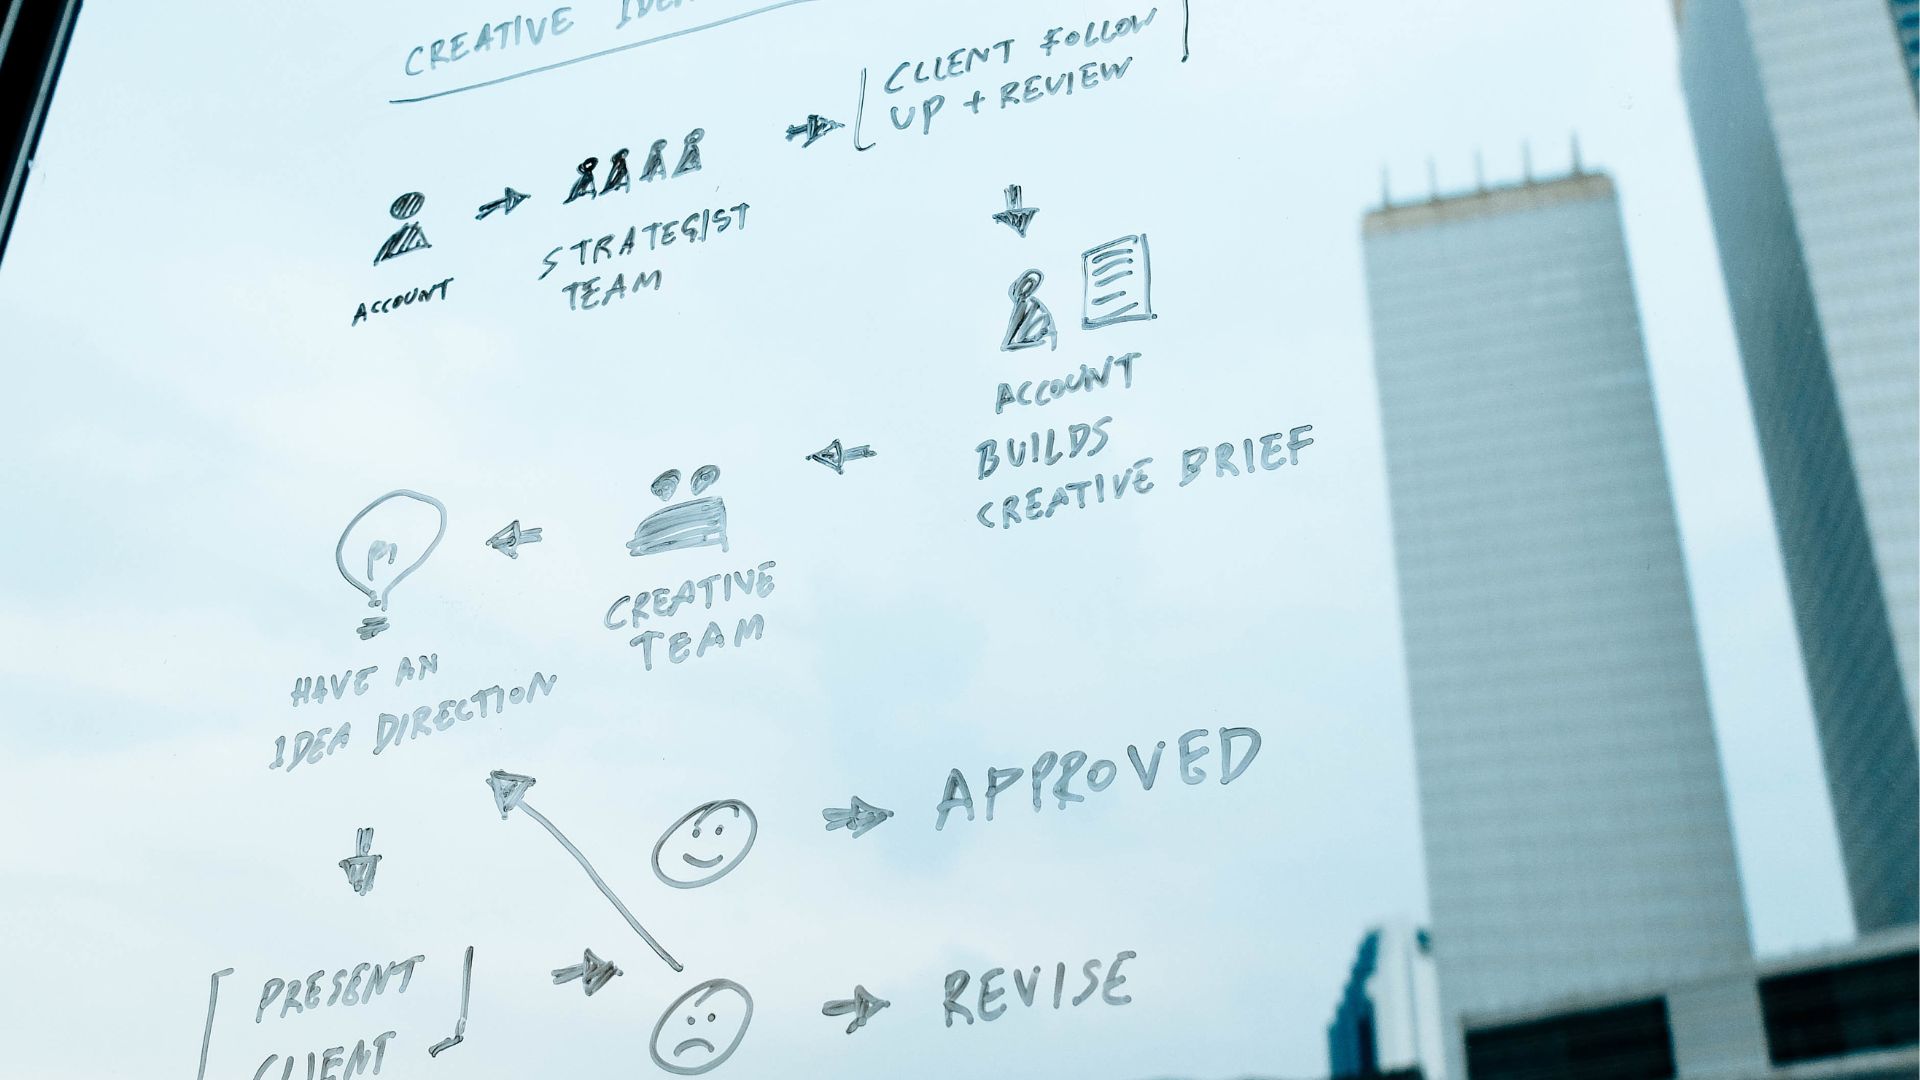
The immediate benefit of process mining is greater visibility into how business processes actually operate. By analysing event data from enterprise systems, organisations can identify bottlenecks, rework, unnecessary variations and deviations from expected workflows.
These findings establish where improvement may be possible, but they do not automatically represent financial value.
An accounts payable team might discover that invoices regularly pass through repeated approval stages. An order-to-cash analysis could identify billing delays associated with particular process variants. In procurement, process mining might expose recurring changes to purchase orders.
Each finding represents an opportunity. The business value emerges when an intervention changes the process and produces a measurable improvement.
That distinction should shape how organisations evaluate their process mining investments.
A reliable measurement approach begins with understanding process performance before improvements are introduced.
Organisations should establish baseline metrics such as processing time, cost per transaction, manual intervention rates, exception frequency and compliance performance. These measures provide a reference point against which subsequent changes can be evaluated.
The choice of metrics depends on the business problem being addressed.
For example, reducing invoice processing time may improve operational efficiency, but the financial benefit depends on whether that improvement reduces expenditure, avoids additional capacity requirements or enables employees to undertake other productive work.
Similarly, faster order processing may improve customer experience without immediately generating additional revenue.
These distinctions matter because operational improvements should not automatically be presented as cash savings.
A credible ROI assessment needs to distinguish between cost reductions, productivity improvements, working capital benefits, and risk reduction, recognising that each creates value in different ways.
Once a baseline has been established, organisations can compare performance following an intervention and determine which benefits can reasonably be attributed to the changes made.
For example, consider a hypothetical accounts payable operation processing 100,000 invoices annually. Process mining identifies repeated manual interventions, and subsequent workflow changes reduce average handling time by two minutes per invoice.
That improvement represents approximately 3,333 hours of processing capacity annually.
However, those hours should not automatically be recorded as a financial saving. A cash benefit would depend on whether the organisation reduces overtime, avoids additional hiring, lowers external processing costs or achieves another measurable financial outcome.
This distinction is essential when presenting results to finance leadership.
The same discipline applies to working capital improvements, avoided penalties and reduced process errors. Benefits should be calculated using documented assumptions, with care taken to avoid double-counting improvements that arise from the same intervention.
A practical ROI calculation compares the financial benefits realised with the total cost of achieving them, including software, implementation, data integration, training and ongoing operational support.
One of the challenges in measuring process mining ROI is ensuring that insights lead to action.
An organisation may identify dozens of improvement opportunities, but unless business owners implement changes and monitor the results, those findings remain analytical outputs rather than realised value.
Sanofi's experience provides a useful example.
In a case study published by QPR, Sanofi describes how its process mining Centre of Excellence adopted a structured Value Realization Framework to connect analysis with measurable outcomes.
The approach aligns initiatives with business process owners' objectives, establishes clear delivery timelines, and uses process data to track the impact of improvements.
The underlying principle is straightforward: process mining initiatives should be evaluated against the business outcomes they are intended to influence, rather than the number of dashboards or analyses produced.
Process mining value also depends on whether improvements can be maintained and extended across the organisation.
Research conducted by Fraunhofer FIT in collaboration with Celonis found that organisations with a process mining Centre of Excellence were approximately nine times more likely to report positive ROI than those without one.
The Celonis–Fraunhofer study highlights the importance of structured governance, organisational support and the ability to scale process mining beyond isolated use cases.
This does not mean establishing a CoE guarantees a financial return. Rather, it reinforces the importance of assigning responsibility for identifying opportunities, implementing improvements and monitoring whether expected benefits are realised.
For organisations with mature process mining capabilities, continuous measurement is particularly valuable. Processes change as systems, policies and operating conditions evolve, meaning an improvement achieved today may not remain effective indefinitely.
Regular monitoring allows organisations to identify emerging inefficiencies and determine whether further intervention is necessary.
The business case for process mining does not end when the technology is implemented. It develops as organisations translate operational understanding into better processes and measurable outcomes.
For CFOs and transformation leaders, a credible assessment of ROI should therefore extend beyond process visibility to examine what changed, why it changed and what financial or operational value followed.
The strongest measurement approaches combine reliable baselines, clearly defined business ownership, transparent financial assumptions and ongoing performance monitoring.
Process mining creates the visibility needed to identify improvement opportunities. Its lasting value depends on what organisations do with those insights, and whether the resulting improvements can be demonstrated in terms the business recognises.
─────────────────────────────────────────────────
How do you calculate process mining ROI?
The standard formula is:
ROI = RealisedBenefits - TotalCosts/TotalCosts x 100
Benefits should include verified financial gains attributable to process improvements. Costs should account for software, implementation, integration, training and ongoing support over the same measurement period.
What KPIs should organisations use to measure process mining ROI?
Relevant KPIs include process cycle time, cost per transaction, rework rates, exception frequency, manual handling time, payment compliance and working capital measures. The appropriate metrics depend on the business process and the improvements being pursued.
How long does it take to demonstrate process mining ROI?
There is no universal timeframe. Results depend on the scope of implementation, data availability, complexity of the process and speed of improvement actions. Organisations should establish a baseline and measurement period appropriate to each initiative.
What is the difference between potential savings and realised savings?
Potential savings estimate the value of an identified improvement opportunity. Realised savings are benefits that have actually occurred and can be supported by evidence. Reduced processing time, for example, may release capacity without immediately reducing expenditure.


Get Updates and announcements from the Verdant Data Team
You can unsubscribe any time. Learn more about our Privacy Policy